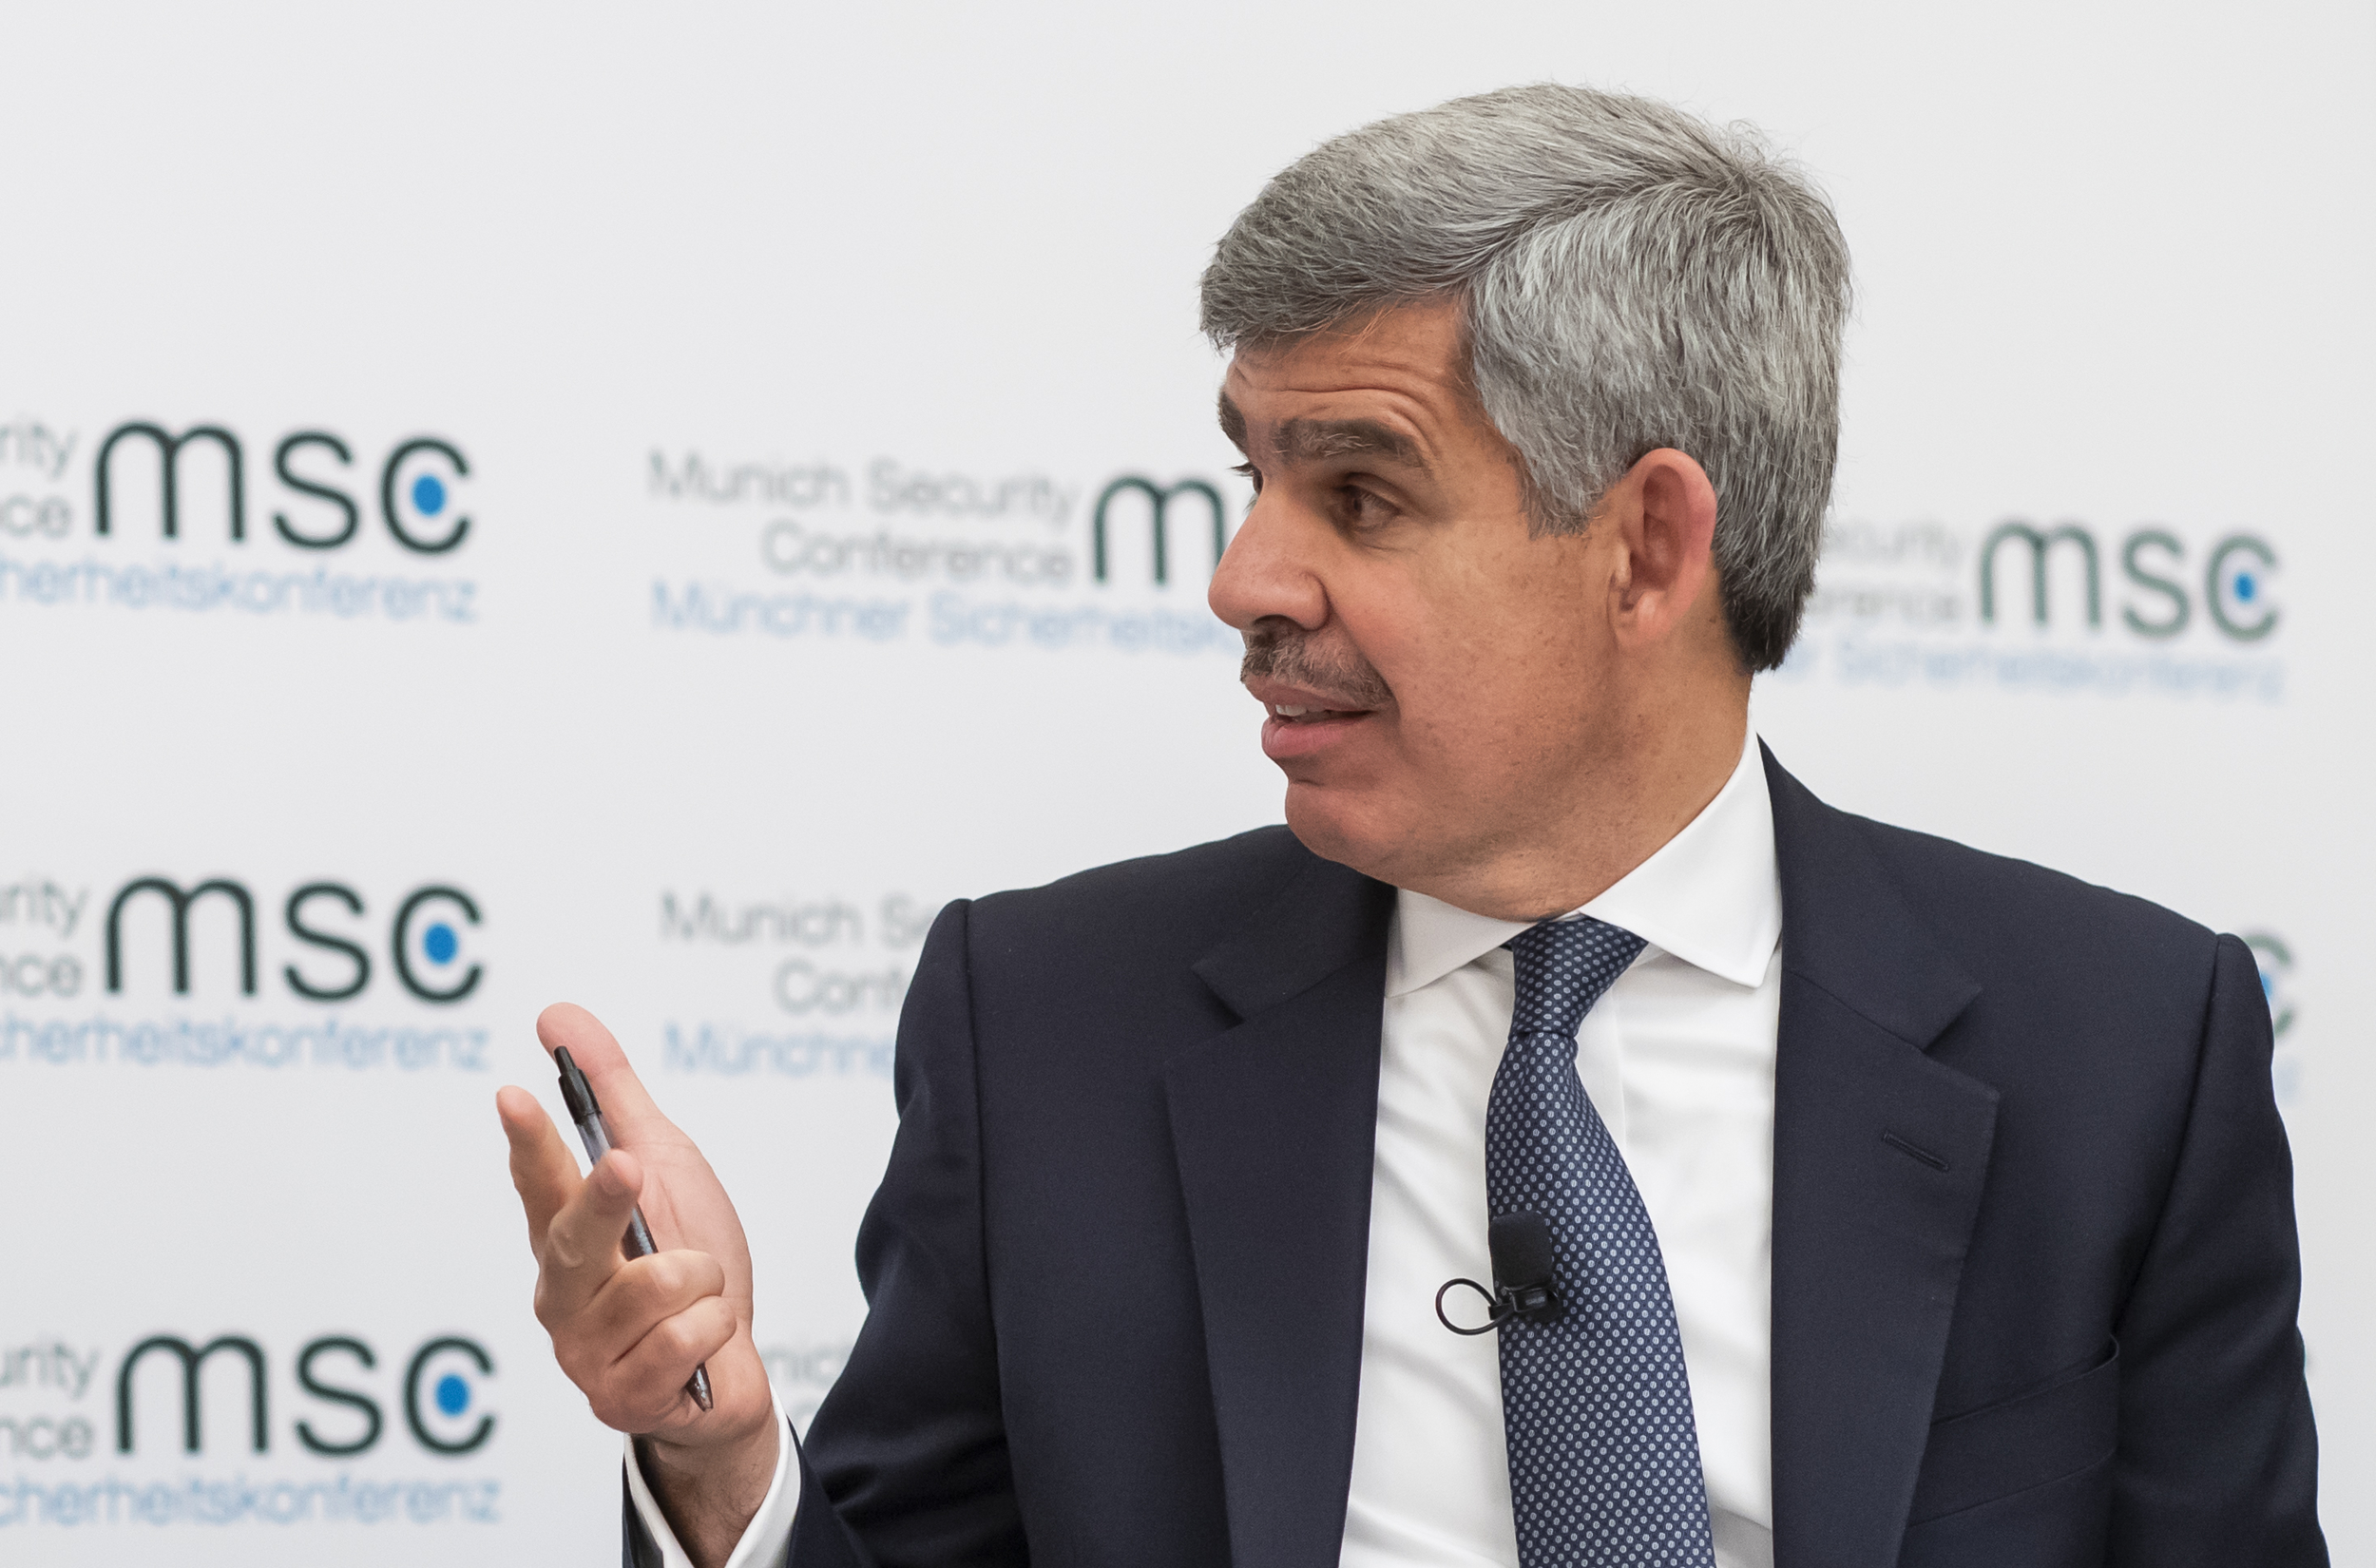
By Brazil Stock Guide — Mohamed El-Erian, one of Wall Street’s most influential economic voices, said Monday’s (October 26) dramatic selloff in Brazilian assets reflected the financial market’s excessive confidence in a presidential victory by Flávio Bolsonaro. According to the former PIMCO CEO and current chief economic adviser to Allianz, investors’ reaction to Luiz Inácio Lula da Silva’s re-election says more about a badly misjudged political consensus than about any fundamental deterioration in Brazil’s economic prospects.
“The massive magnitude of today’s selloff in Brazilian assets is less about Brazil’s underlying outlook and more about just how confident—and wrong—the consensus view on finance was with respect to a Bolsonaro win,” El-Erian wrote in a post on X. His assessment suggests that a substantial part of the market turmoil stemmed from investors having to unwind positions built around an electoral outcome that never materialized.
A professor at the University of Pennsylvania’s Wharton School, El-Erian previously served as CEO and co-chief investment officer of PIMCO, one of the world’s largest fixed-income investment managers. He also led Harvard Management Company, which oversees the university’s endowment, and held senior positions at the International Monetary Fund. He currently chairs Gramercy Funds Management. His views on monetary policy, macroeconomic risks and global capital flows are closely followed by institutional investors and policymakers worldwide.
His comments came during one of the most turbulent trading sessions in Brazil’s recent financial history. The benchmark Ibovespa index plunged 13.88% to close at 176,608 points on Monday, the first trading day after the presidential runoff. The index had fallen more than 17% intraday, triggering a temporary trading halt on Brazil’s B3 stock exchange. It was the index’s steepest daily decline since March 2020. Meanwhile, the US dollar surged 8.21% against the Brazilian real to R$5.403, its largest single-day percentage gain since January 1999.
The contrast with the market’s response to the first round of voting helps explain El-Erian’s argument. On October 5, after Flávio Bolsonaro finished ahead of Lula in the initial ballot, the Ibovespa surged 7.70% to a record high, while the dollar fell roughly 4.1% against the real. Investors had interpreted the result as strengthening the prospects for a change in government. Three weeks later, Lula’s victory forced markets to reassess those expectations, triggering a reversal of positions that amplified volatility.
El-Erian’s assessment does not suggest that concerns over Brazil’s fiscal outlook under another Lula administration have disappeared, nor that the entire selloff can be attributed to misguided positioning. It does, however, draw an important distinction between a genuine deterioration in economic fundamentals and a sharp repricing caused by expectations that proved wrong. Without reliable data on the scale of investors’ election-related positions, it is impossible to determine precisely how much each factor contributed to the decline. For El-Erian, however, the extraordinary magnitude of the market reaction points above all to the cost of a financial consensus that got the election wrong.


Leave a Reply