By Brazil Stock Guide – Nu Holdings launched operations in the United States on Thursday, expanding beyond Latin America and putting to the test, in the world’s largest financial market, the low-cost model that helped the Brazil-founded digital bank build a customer base of more than 140 million.
The U.S. rollout is initially being carried out through a partnership with Lead Bank, an FDIC-insured U.S. lender. The structure allows Nubank to launch banking products while it completes the process of obtaining its own U.S. banking charter: customer deposits are held at the partner bank and may qualify for FDIC insurance subject to applicable limits and conditions, while Nu provides the digital experience and distributes the products.
The initial offering includes a deposit account yielding 3.5% a year, a no-annual-fee Mastercard credit card with 1.5% cashback, and fee-free domestic and international money transfers. During the launch event, Nubank co-founder and U.S. chief Cristina Junqueira said the company plans to raise the account yield to 4.5% for customers who pair it with the credit card, while cashback could rise to 2% for customers who set up direct deposit.
Nu applied for a U.S. national bank charter with the Office of the Comptroller of the Currency in 2025 and received preliminary conditional approval in January. Until that regulatory process is completed, the Lead Bank partnership effectively serves as a bridge, allowing the company to begin testing its products and customer-acquisition strategy in the U.S. market.
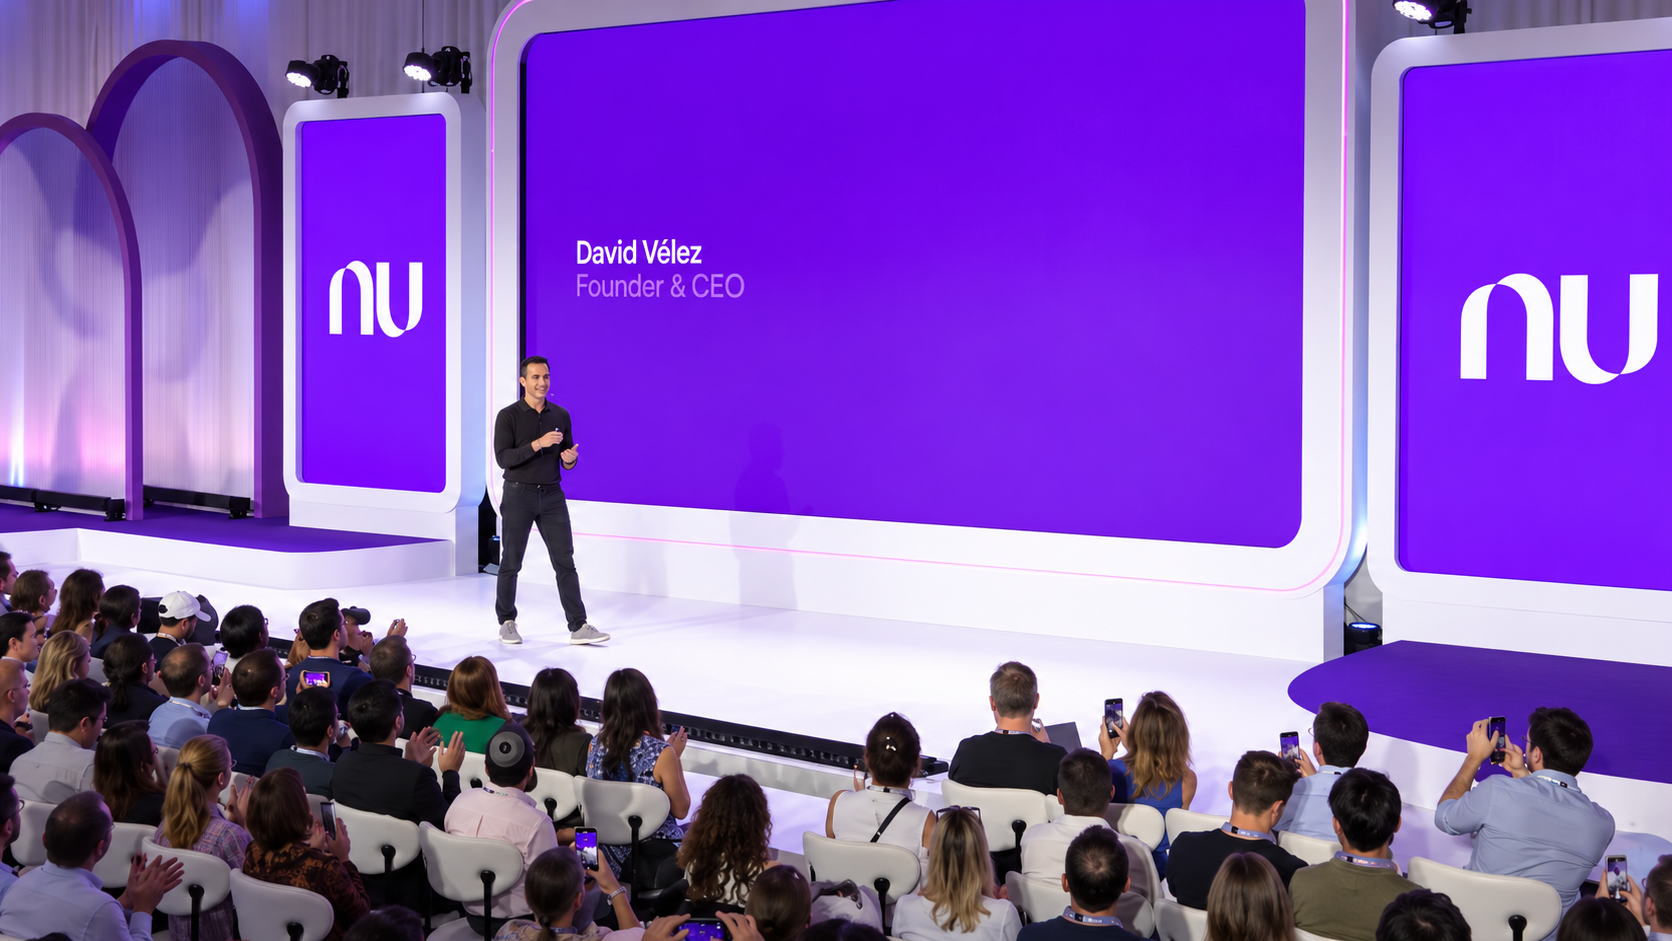
“Brazil, Mexico and Colombia still offer enormous opportunities for growth. It’s day one for us, even in Brazil. But they have also taught us something important: the model can travel,” founder and Chief Executive David Vélez said during the launch event. Vélez argued that problems such as high costs, complexity and poor customer service are not unique to any one financial system.
Nubank was founded in São Paulo in 2013 after Vélez saw room for a simpler, digital-first financial institution in a market dominated by large incumbent banks. At Thursday’s event, he again recalled his experience opening a bank account after moving to Brazil in 2012, describing a bulletproof revolving door, armed security guards, a wait of more than an hour and a process that ultimately took months before his credit card arrived.
Nubank’s first product was a purple, no-annual-fee credit card. According to Vélez, the company reached 1 million customers in less than two years, hit 10 million in about five years and went public on the New York Stock Exchange in 2021. Its product offering gradually expanded into deposits, lending, investments and other financial services.
The company began testing its international expansion in Mexico in 2018 and entered Colombia in 2021. Mexico now has more than 16 million Nu customers and the business is profitable, according to Vélez. “Three countries, different systems, but the same basic customer need: people just want to be treated well,” he said, referring to Nu’s experience across its three Latin American markets.
The United States, however, presents a different challenge. The market is less concentrated, large banks already offer sophisticated digital services and competition from fintechs and digital lenders including Chime, SoFi, Ally and Revolut is well established. Services such as Zelle, Venmo and PayPal are also deeply embedded in consumer payment habits, making it harder for a new entrant to differentiate itself simply by being digital. InvestNews, a news outlet affiliated with Nubank, reported that the company itself expects marketing and customer-acquisition costs to be higher in the U.S.
One of Nu’s main competitive bets is its cost structure. According to InvestNews, the company estimates that it costs about $1 a month to serve an active customer, while Junqueira compared that figure with roughly $20 at traditional U.S. banks. She also told the publication that a U.S. operation with 10 million customers could have an economic impact comparable to 100 million customers in Brazil because of the higher revenue potential per user.
Alongside its U.S. launch, Nu introduced Nu Global, a multi-currency account initially aimed at customers in more than 35 countries. The platform will use dollar- and euro-pegged stablecoins, offering annual yields of 3.5% on funds converted into USDC and 2.2% on EURC, as well as a virtual card and access to a curated selection of digital assets including bitcoin and ether. The company says transfers between supported markets can be made quickly and without transfer fees.
“Sending money should be as easy as sending a text message, real-time, for free,” Vélez said as he outlined the longer-term vision for Nu Global. The strategy goes beyond opening banking operations country by country: by connecting users across different markets, Nu ultimately aims to build an international payments network and deepen the range of financial services customers use within its platform.
The expansion comes as Nubank combines rapid growth with strong profitability. According to InvestNews, the group posted record second-quarter net income of $1.06 billion, up 49% from a year earlier, with a 33% return on equity.
The U.S. bet, however, is still starting small: the operation has about 60 employees, while 97% of the group’s roughly 10,000 staff remain focused on Brazil, Mexico and Colombia. The move opens a new avenue for growth, but also begins a tougher test of whether a banking model built in Brazil can preserve its advantages in one of the world’s most competitive financial markets.


Leave a Reply