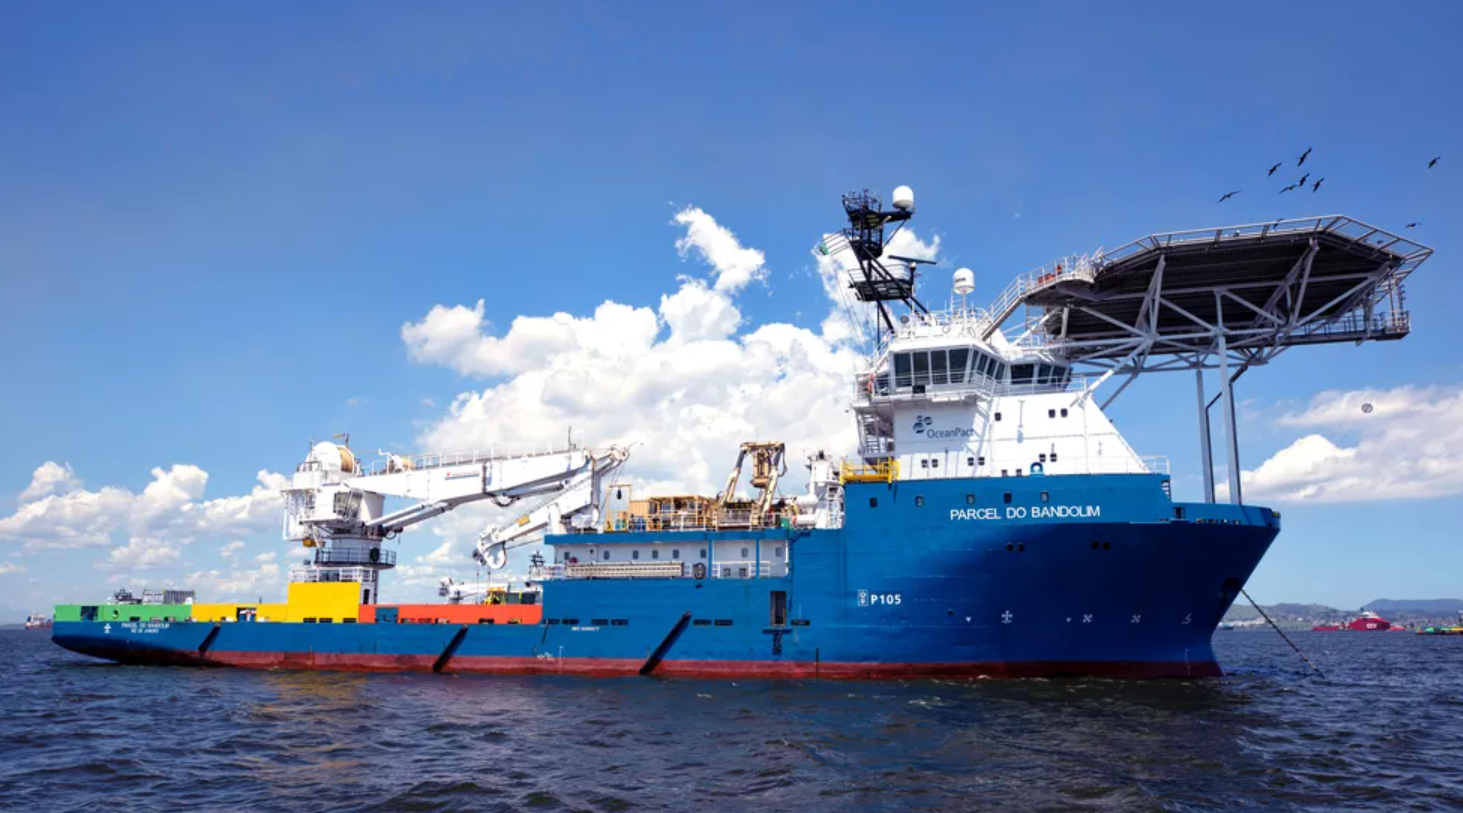
By Brazil Stock Guide – Brazil’s antitrust watchdog Cade has cleared the combination of OceanPact (OPCT3) and CBO without restrictions, allowing the two offshore services companies to move closer to creating a group valued at R$4.5 billion with a combined fleet of 73 vessels. The decision was reported by Valor Econômico on Monday, July 27, citing a market disclosure from OceanPact.
The ruling was issued by Cade’s General Superintendence and is not yet final. An interested third party may appeal, while members of Cade’s tribunal may call the case up for review under the agency’s rules.
Once the clearance becomes definitive, the boards of OceanPact and CBO will meet to confirm that all conditions precedent have been fulfilled and set the closing date.
The unconditional approval is significant because Petrobras (PETR3, PETR4), the dominant buyer of offshore support services in Brazil, joined the proceeding to raise concerns about concentration in specialized vessel categories used in pre-salt operations.
A 73-vessel offshore group
OceanPact and CBO announced the transaction on February 27 and notified Cade in April. The deal will be implemented through the incorporation of CBO’s holding company into OceanPact.
The combined group would operate 73 offshore support vessels, including 28 from OceanPact and 45 from CBO. It would also have annual revenue of more than R$4 billion and a contract backlog of approximately R$14 billion.
The companies expect the transaction to improve vessel allocation, expand their ability to compete for larger contracts and generate commercial and operational synergies. The merger would also bring together offshore logistics, subsea operations, environmental services and maritime engineering capabilities.
Across the broader offshore support vessel, or OSV, market considered in the Cade proceeding, the merged company would hold a 15.4% share.
That headline figure was central to the companies’ defense of the transaction. OceanPact and CBO argued that the combined group would remain exposed to competition from several Brazilian and international operators.
Petrobras focuses on specialized vessels
Petrobras used the review to challenge a broad definition of the offshore vessel market. The oil producer argued that OSVs perform different functions and cannot always be treated as substitutes for one another.
A platform supply vessel, for example, is not necessarily capable of replacing a vessel designed for subsea interventions. An oil-spill response vessel also performs a different role from a ship equipped to support remotely operated vehicles.
Petrobras’s main concern centered on ROV Support Vessels, or RSVs. These vessels support underwater inspections, maintenance and interventions involving remotely operated equipment, making them an essential part of deepwater and pre-salt operations.
OceanPact and CBO would jointly operate 14 RSVs — nine from OceanPact and five from CBO. That represents 40% of the 35 vessels included in the segment assessed by Cade.
If the analysis is restricted to Brazilian-flag RSVs, the combined share rises to 45%.
The concentration is lower in other categories. In the platform supply vessel and oil-spill response segment, the companies would operate 40 vessels, equivalent to 19.7% of a 203-vessel market. In subsea support vessels excluding pipe-laying units, the merged group would hold 16 vessels, or 20.5% of the segment.
Petrobras seeks a voice in supplier consolidation
The OceanPact-CBO proceeding was the second recent offshore vessel merger review in which Petrobras sought to influence Cade’s assessment.
The company previously tried to join Tidewater’s acquisition of Wilson Sons Ultratug as an interested third party. Petrobras also appealed Cade’s unconditional clearance of that transaction.
Cade rejected the request to join the case, declined to hear the appeal and confirmed the approval without restrictions. The decision later became final.
Petrobras had greater access in the OceanPact-CBO review. Cade’s General Superintendence admitted the company as an interested third party, allowing it to submit data on procurement procedures, regulatory barriers and foreign-flag vessels blocked from individual contracts.
The involvement highlights Petrobras’s attempt to preserve bargaining power and operational flexibility in a supply chain that supports Brazil’s offshore production system.
Petrobras defines technical specifications, contract durations, tender lots and commercial conditions when hiring offshore vessels. At the same time, the company depends on a relatively limited pool of specialized assets to maintain production from deepwater fields.
OceanPact and CBO point to Petrobras’s buyer power
OceanPact and CBO rejected the argument that the merger would materially weaken competition. They said Petrobras holds substantial buyer power and can shape competitive conditions through its procurement strategy.
The companies cited Petrobras’s own tender data to support their position. Between July 2021 and January 2026, the oil producer conducted 64 competitive procedures that resulted in 39 different winning companies from at least 11 economic groups.
CBO won four of those procedures, while OceanPact won another four. Together, the companies secured eight of the 64 tenders, or 12.5% of the total.
OceanPact and CBO also argued that RSVs should not be treated as an entirely closed market. Other vessel types may be adapted for ROV operations, they said, while Petrobras itself determines the technical requirements and eligible assets for each tender.
The companies maintained that the regulatory issues raised by Petrobras existed before the transaction and therefore could not be treated as consequences of the merger.
Foreign vessels become a point of contention
Petrobras also questioned how easily foreign vessels can compete in Brazil. Local rules give preference to Brazilian-flag ships or vessels registered under the country’s special registry regime.
Before a foreign vessel can be chartered, the market must undergo a process before waterway regulator Antaq to determine whether a suitable Brazilian vessel is available. A foreign unit may be blocked from a specific contract if a qualifying local vessel can provide the service.
Petrobras argued that this process limits the ability of foreign vessels to constrain prices and increase capacity in specialized segments.
OceanPact and CBO said the regulation does not create a permanent barrier. According to the companies, a blocked foreign vessel is not prohibited from operating in Brazil; it is only prevented from serving a particular contract when an eligible Brazilian or equivalent vessel is available.
The companies also noted that foreign ships already represent a significant part of the domestic fleet. Brazil had 473 offshore support vessels in operation in December 2025, including 90 foreign-flag units, or 19% of the total.
A separate report from offshore support industry association Abeam showed 481 vessels operating in the country in February 2026, including 390 Brazilian-flag ships and 91 foreign-flag units.
Cade sides with the companies
By approving the merger without remedies, Cade’s General Superintendence concluded that the combination would not eliminate effective competition, despite the higher concentration in RSVs.
The decision supports OceanPact and CBO’s position that broader rivalry, the possibility of adapting vessels, the presence of international operators and Petrobras’s buyer power are sufficient to constrain the combined company.
The review nevertheless exposed the strategic importance of offshore support assets for Petrobras. The company does not treat specialized vessels as ordinary suppliers, but as part of the operating backbone that keeps Brazil’s pre-salt production running.
The merger will move to closing if no interested party appeals and Cade’s tribunal does not call the case up for further examination. OceanPact and CBO must then confirm that the remaining conditions under the transaction agreement have been satisfied.


Leave a Reply