
By Brazil Stock Guide — The breakup of Brazilian fashion group Azzas 2154 is emerging as more than a reversal of its two-year-old merger strategy: S&P National Ratings says the transaction is also an alternative to resolving conflicts between the company’s reference shareholders, while potentially leaving the resulting businesses with weaker credit profiles.
S&P downgraded Azzas’ issuer and debt ratings to brAA from brAA+ and placed them on CreditWatch with negative implications, signaling the possibility of another downgrade within 90 days. The ratings agency’s assessment offers one of the clearest external readings yet of what went wrong after the combination of Arezzo&Co and Grupo Soma, completed in July 2024.
S&P said the planned separation could weaken the companies’ business-risk profiles because of reduced scale, the reallocation of liabilities and the disappearance of synergies originally expected from the merger.
More pointedly, the agency said the transaction represents “an alternative” to resolving conflicts among Azzas’ reference shareholders, which it considers a negative factor in its assessment of management and governance.
The numbers fell short
The deterioration was already visible before the split was announced. In the 12 months through June 2026, Azzas’ consolidated net revenue fell 1.6% year on year to R$11.4 billion, below S&P’s R$12.8 billion expectation for 2026. Adjusted EBITDA margin stood at 13.3%, versus the ratings agency’s previous projection of 15.7%.
S&P attributed the weaker performance partly to lower sell-in volumes as franchise inventories normalized, but also highlighted a tougher macroeconomic environment and the absence of the integration gains originally expected from the merger.
The agency also pointed to the continued decline in Azzas’ market value following shareholder disagreements and successive management changes. That combination raises the possibility that Azzas could be downgraded again even before the breakup is completed.
Creditors enter the equation
The restructuring is also not purely an equity story. Completion of the transaction is subject to regulatory and corporate steps, including CADE approval, the listing of Soma shares on B3 and waivers from holders of debentures and real-estate receivables certificates, or CRIs, because existing debt documents contain restrictions tied to corporate events.
Failure to obtain those waivers could trigger the acceleration of debentures and CRIs, S&P said. The agency estimates Azzas has about R$3.4 billion of senior unsecured obligations under the debt structure considered in its recovery analysis, including debentures, CRIs, bank debt and an estimate for the cancellation of operating leases.
In a hypothetical default scenario, S&P estimates debenture holders would recover roughly 60% of their claims.
Undoing the merger
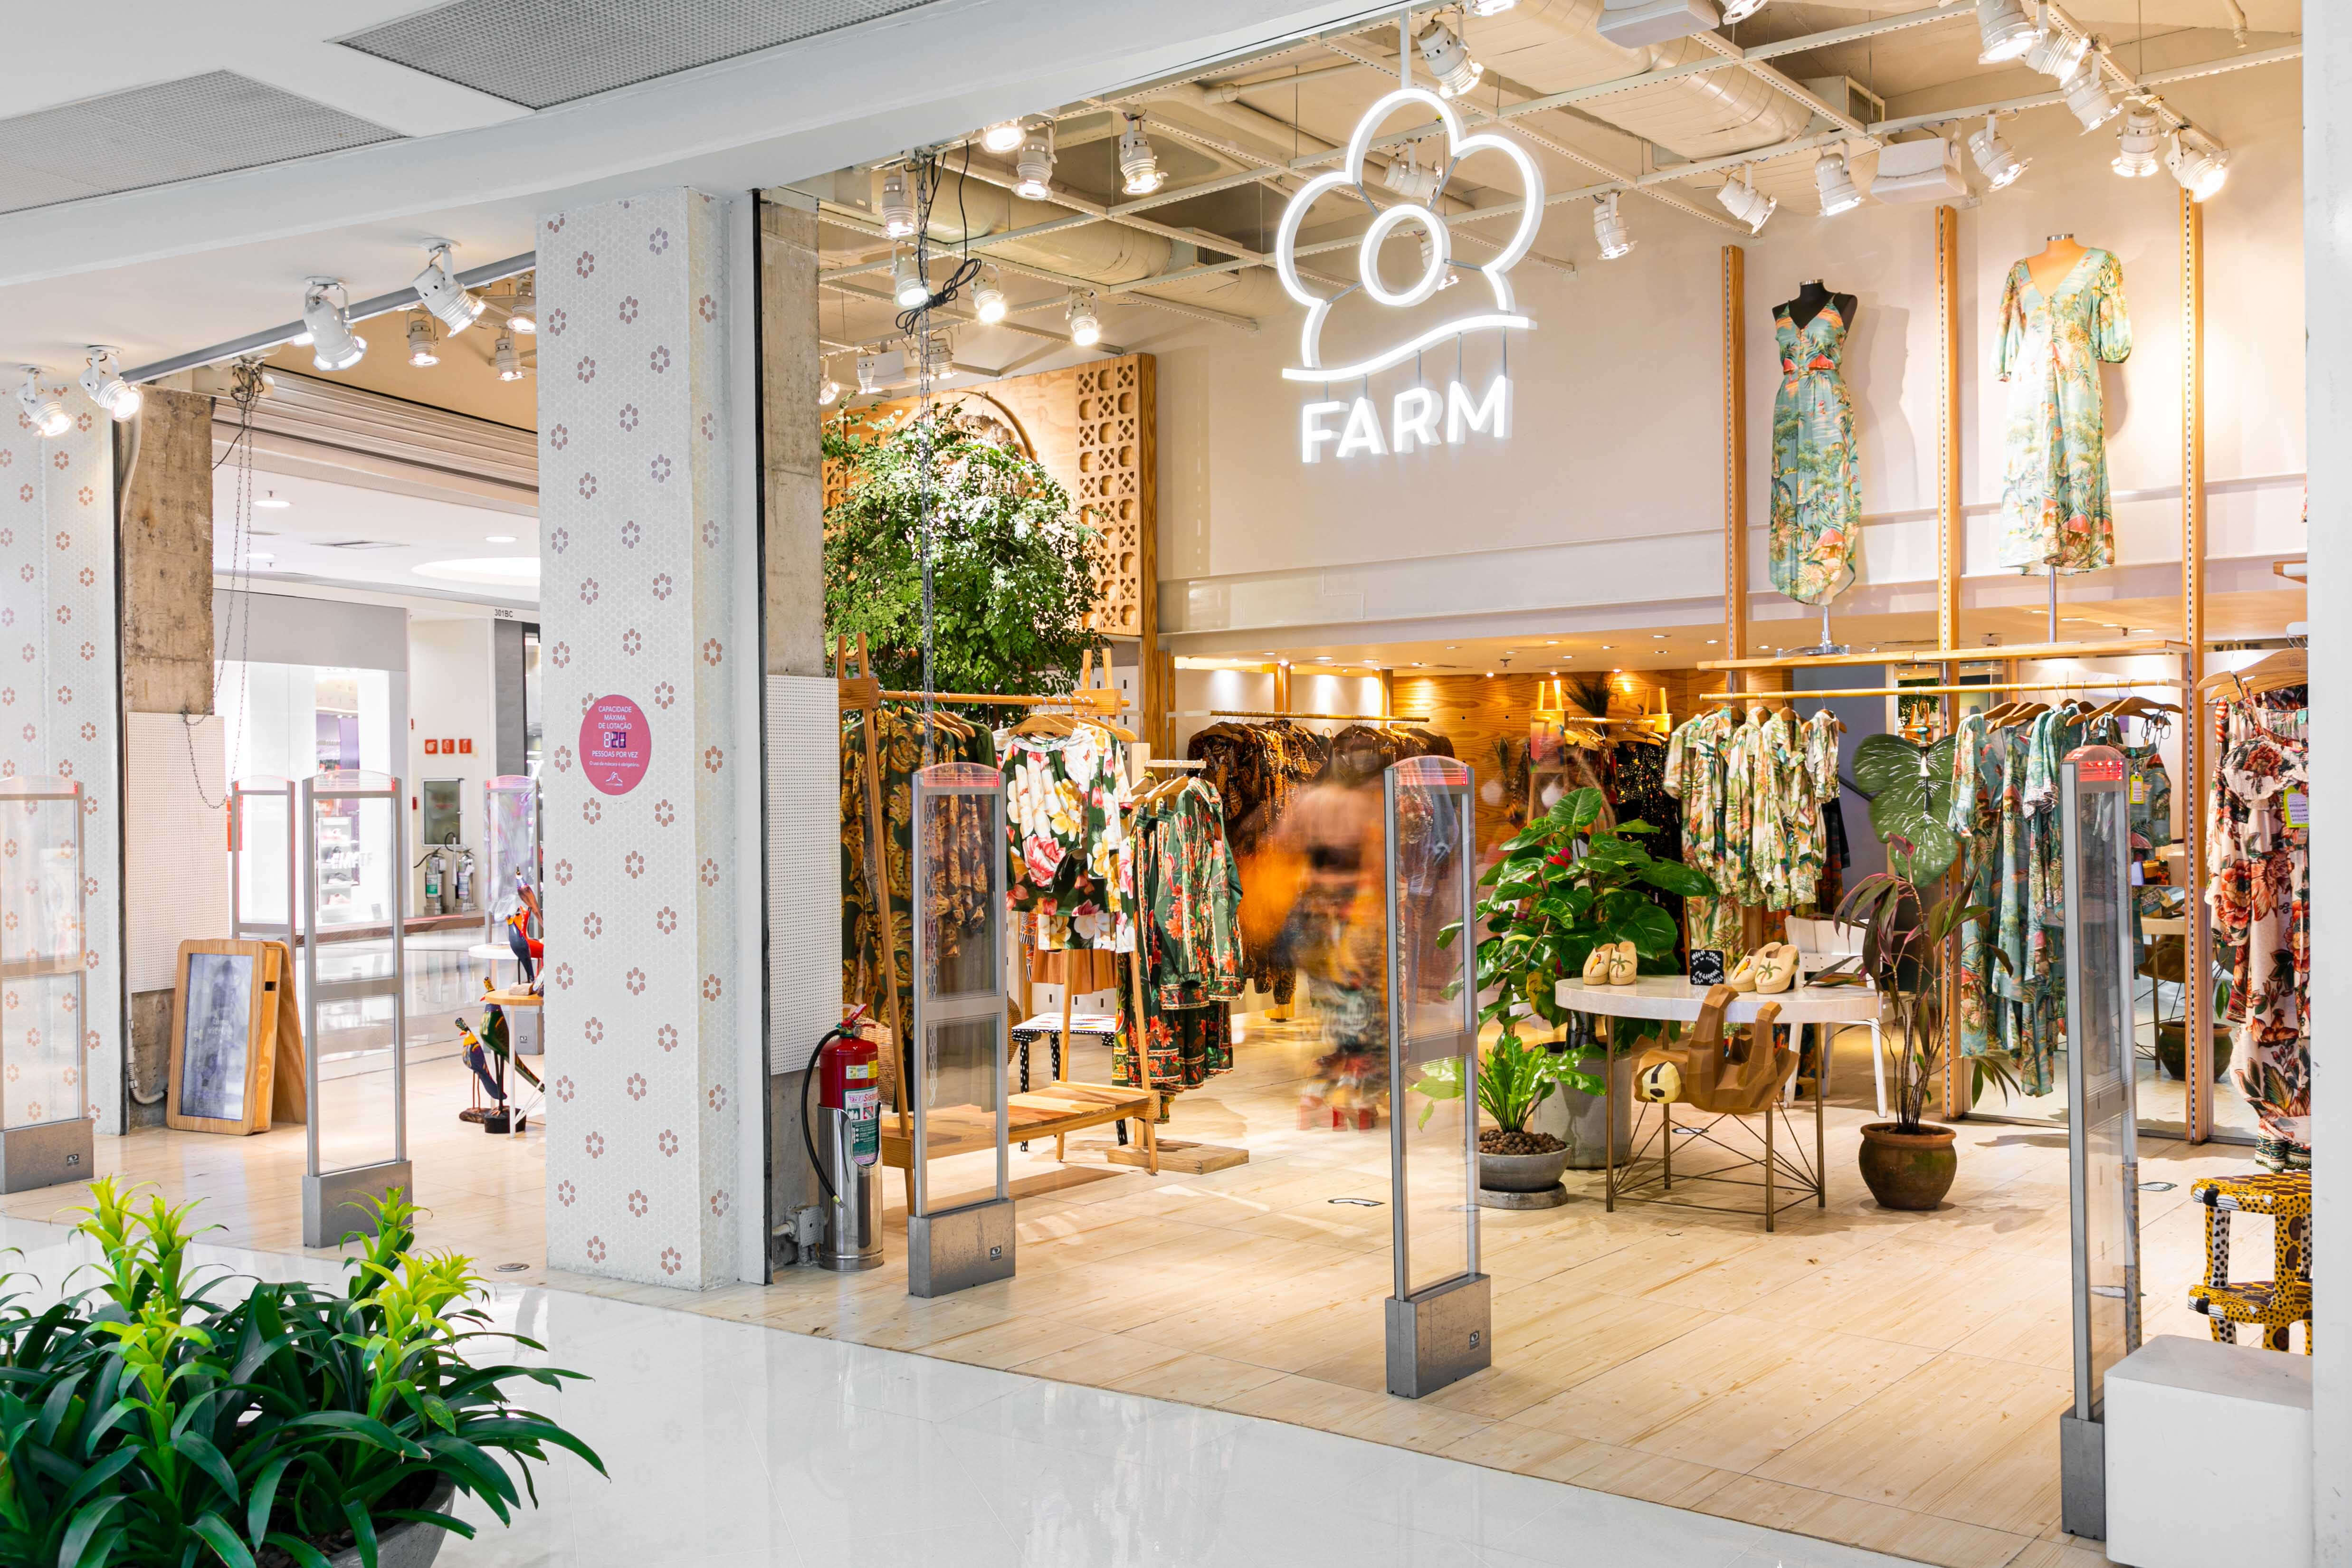
Under the proposed restructuring, the group’s brands will ultimately be divided across three entities. Arezzo & Co will hold footwear and handbag brands as well as Hering and related businesses, while Soma will house most of the group’s women’s and men’s apparel labels. Farm, Farm Global and Fabula will be placed in a third entity controlled by Arezzo & Co, with Soma retaining a significant equity interest.
The structure effectively unwinds much of the strategic logic behind a combination that was presented in 2024 as a way to create a larger, more diversified Brazilian fashion platform. Two years later, S&P’s assessment suggests the separation carries its own costs: smaller operating platforms, weaker credit metrics and less financial flexibility.
For investors, the key question is therefore no longer simply whether breaking Azzas apart can end the shareholder dispute. It is whether the businesses emerging from the split will be financially stronger on their own than the company they are leaving behind.


Leave a Reply