
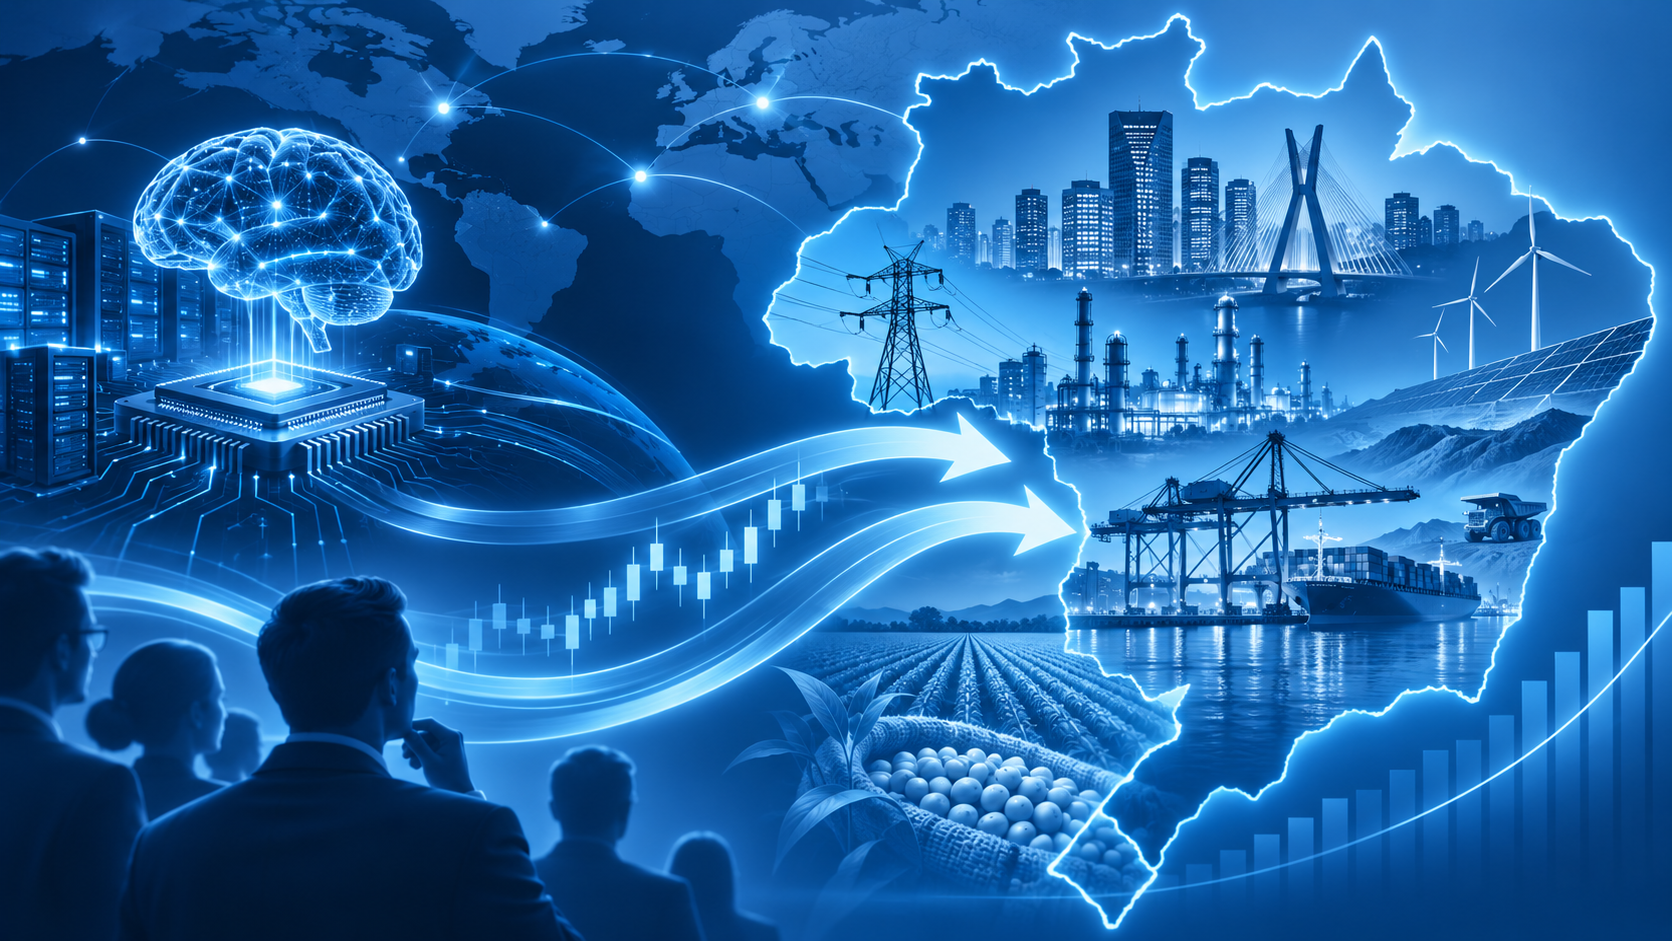
Brazil may emerge as an unexpected beneficiary of one of the central contradictions of the current global investment cycle: the more capital becomes concentrated in artificial intelligence in the United States, the stronger the incentive for investors to seek alternatives in economies less dependent on technology. At the same time, the reelection of President Luiz Inácio Lula da Silva could create a more favorable political environment for Chinese investment in Brazilian industrial assets. These are two distinct trends, but they may converge toward the same outcome: putting Brazil back on the radar of global investors.
André Moor, head of Investment Banking at Bradesco BBI, believes Chinese investors may feel more comfortable with the continuity of an administration perceived as friendlier toward Beijing. The recent transaction involving CSN Cimentos and China’s Huaxin illustrates that interest. But there is an important difference from the past: Chinese buyers have become more familiar with the Brazilian market, rely on local teams and increasingly apply rigorous financial discipline to their investment decisions. This is no longer about capital willing to pay almost any price for a strategic foothold. It is about companies identifying industrial opportunities and negotiating accordingly.
The picture takes on another dimension when viewed from the perspective of Western investors. George Costa e Silva, head of Equity Capital Markets at Bradesco BBI, described conversations with major international asset managers seeking to diversify portfolios heavily concentrated in technology and artificial intelligence. In this context, Brazilian oil, energy, infrastructure and commodity assets offer something that America’s largest technology companies do not: exposure to traditional industries with different revenue drivers and risk profiles.
The relative size of global financial markets helps explain the opportunity. Even a marginal reallocation of capital managed by major international funds could have a substantial impact on Brazilian asset prices. But there is an important caveat: if a sharp correction in AI-related stocks triggers a global wave of risk aversion, Brazil would probably suffer in the initial selloff as well. Diversification could benefit the country after the shock, not necessarily during the turmoil. Having less exposure to AI does not mean being insulated from an international financial crisis.
There is also a particularly interesting paradox. Brazil could attract investors seeking to reduce their financial exposure to artificial intelligence while simultaneously receiving investment in the physical infrastructure required to support it. Data centers represent this second opportunity. Bradesco BBI executives point out that restrictions on the construction of large facilities in the United States could create openings for other countries. Brazil has energy resources, a substantial domestic market and room for expansion, but it must offer legal certainty, competitive electricity costs and predictable rules governing data storage and processing. Potential advantages do not automatically translate into actual projects.
Rare earth minerals illustrate another dimension of the challenge. Geopolitical interest in strategic minerals increases the potential value of Brazil’s reserves, but it does not eliminate the long journey from identifying a deposit to achieving commercial production. Moor noted that developing a mine can take five to ten years, including exploration, permitting and construction. Specialized investors may enter earlier, acquiring projects still in their initial stages. Larger institutional investors, however, tend to require greater operational maturity. Possessing natural resources is an advantage, but turning them into competitive production requires time, investment and institutional capacity.
The same logic applies to investors from the Middle East. According to Danilo Ene Borges, head of M&A and Financial Sponsors at Bradesco BBI, investors from the region remain interested in Brazilian infrastructure opportunities. The challenge is that the cost of capital has risen globally. Investors are demanding higher returns, financing has become more expensive, and assets must demonstrate stronger cash-generating capacity. In this environment, buyers may compete aggressively for the most attractive businesses, while riskier assets or those with less predictable earnings face growing difficulties. Capital remains available, but it is becoming increasingly selective.
This is where Brazil’s domestic economic policy returns to the center of the discussion. Foreign investors’ willingness to consider the country does not remove the effects of high interest rates, fiscal uncertainty and regulatory obstacles. Nor does it mean the government must simply accommodate every demand from financial markets. The challenge is to establish a sufficiently predictable environment in which long-term productive investments can move forward regardless of political fluctuations. Industry, infrastructure and mineral development depend on decisions that extend beyond individual administrations and electoral cycles.
Brazil could play three roles simultaneously: a destination for Chinese capital, a major commodity supplier and an alternative to the global concentration of investment in technology. But an opportunity should not be mistaken for a transformation that is already assured. The true measure of success will be the country’s ability to turn international interest into factories, infrastructure, production, jobs and competitive businesses. In a world marked by wars, geopolitical tensions and uncertainty over the future of artificial intelligence, Brazil’s advantage may lie precisely in its geographic distance from the world’s main conflict zones and in the strength of its real economy.


Leave a Reply